Friday, 2pm, in a meeting room at a Paris VC firm. The partner opens your deck and says: "Go ahead, I'm listening." You think you're about to give one pitch. In reality, you're facing three different exercises: the PDF deck (read on its own, in about two minutes according to DocSend1), the oral pitch (3 to 15 minutes in the meeting, where you carry the story), and the French-style Q&A (where the deal is won or lost). This guide covers the structure of each, timing by format, the 10 most common trick questions with answer scripts, the follow-up protocol, and how to choose the right VCs to approach.
Before the pitch, pick the right VCs
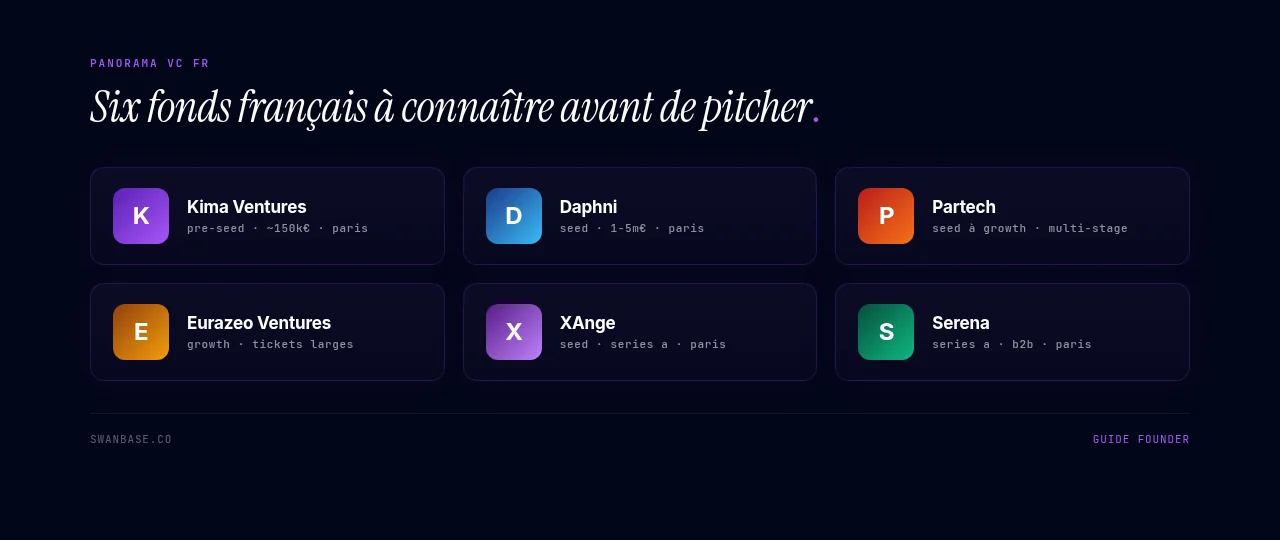
A pitch is won first through targeting. Before you send a single deck, ask one question: has this fund already backed a startup like yours, at your stage, for the amount you're raising?
Test the fit (stage, ticket, sector, geography)
Start with stage and ticket size: a Series B fund doesn't do Seed, and asking for €1.5M from a fund whose average ticket is around €300k works no better than the reverse (French market benchmarks: pre-seed from angels and micro-funds €50k to €500k, Seed VC €500k to €2M, Series A €2M to €10M). Then check the sector thesis and geography by reading the fund's last 20 deals on LinkedIn or Crunchbase rather than its "About" page. A B2B SaaS fund won't finance a B2C marketplace, most French funds stop at France and Europe, and the few funds looking in from London or Silicon Valley (Sequoia, Index, Accel) have a high bar for entry.
Do your homework on the VC
Before each meeting, spend at least two hours on:
- The fund's last 10 investments (who, how much, what stage).
- The partner who covers your vertical: that's the person you'll meet once your file has moved up internally.
- Podcasts and essays published by the partners: they give away their thesis for free.
- Recent exits. A fund with no exit in 5 years is nearing the end of its cycle, with reduced capacity to invest.
How to land the first meeting (warm intro vs. cold)
The best VCs read few cold decks. They read decks recommended by their portfolio founders or co-investors. The warm intro is still the best way in.
Three ways to get an intro:
- A portfolio founder introduces you. Ask them to review your deck first.
- Another VC refers you (often when they can't invest themselves but believe in the deal).
- A senior operator in the sector (advisor, former CEO, recent exit).
A generic cold email gets a 1 to 2% response rate, according to Founders Capital. A targeted send to investors active at your stage does much better, and only with an ultra-specific subject line: "[My startup] [traction figure] [sector] [ticket sought]". Skip the "Hello, I'd like to present my project": it goes straight to the archive. Send that first email to the associate or analyst, whose job is to source deals; the partner decides later, in the meeting and then in the investment committee. The full method is in our VC cold email guide. Even before the email, an investor who has read you online already knows who you are: see our article on founder-led content before a raise.
The pitch deck structure VCs expect
Every VC expects the same structure. It's a convention: following it won't win you the deal, but breaking it will lose it. Industry sources converge on 10 essential slides2, plus 3 bonus slides depending on the case3.
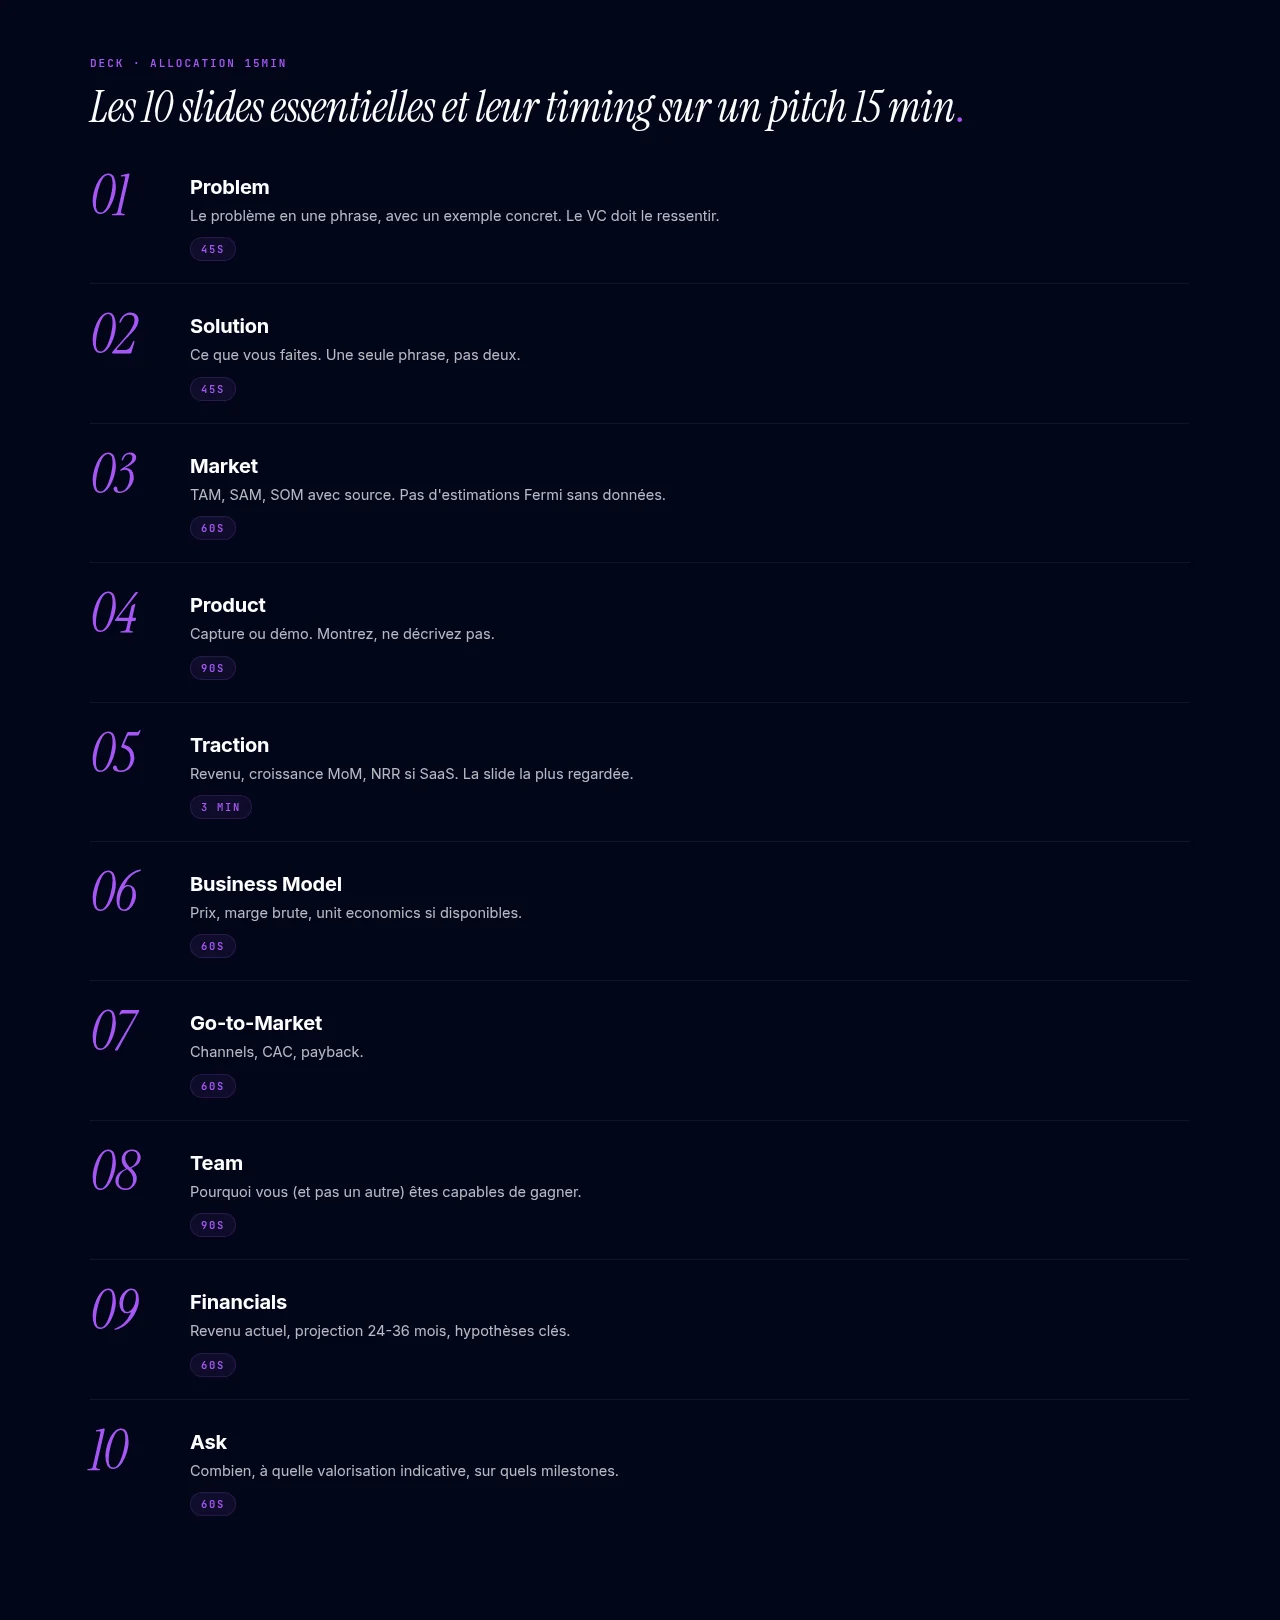
The 10 essential slides
- Problem. The problem in one sentence, with a concrete example. The VC has to feel it.
- Solution. What you do, in one sentence. Just one.
- Market. TAM, SAM, SOM with sources. No Fermi estimates without data.
- Product. Screenshot or demo. Show it instead of describing it.
- Traction. Hard numbers: revenue, users, MoM growth, NRR for SaaS, GMV for marketplaces. This is the most-viewed slide.
- Business Model. How you make money. Pricing, gross margin, unit economics if available.
- Go-to-Market. Channels, CAC, payback.
- Team. Photos, names, backgrounds. Why you, specifically, can win.
- Financials. Current revenue, 24 to 36 month projection, key assumptions.
- Ask. How much you're raising, at what indicative valuation, toward which milestones.
To build the deck slide by slide, including the meta-problem and the "we cracked the code" slide, follow our 14-slide pitch deck structure.
3 optional bonus slides
- Vision (slide 11). Where the company goes in 10 years. Useful for funds that invest in visions (Index, Sequoia).
- Moats (slide 12). Why a competitor can't copy you: network, data, patents, brand, switching costs.
- Roadmap (slide 13). What you'll do with the cash over the next 12 to 18 months. Especially useful if your traction is early.
The pitch, section by section (timing per slide)
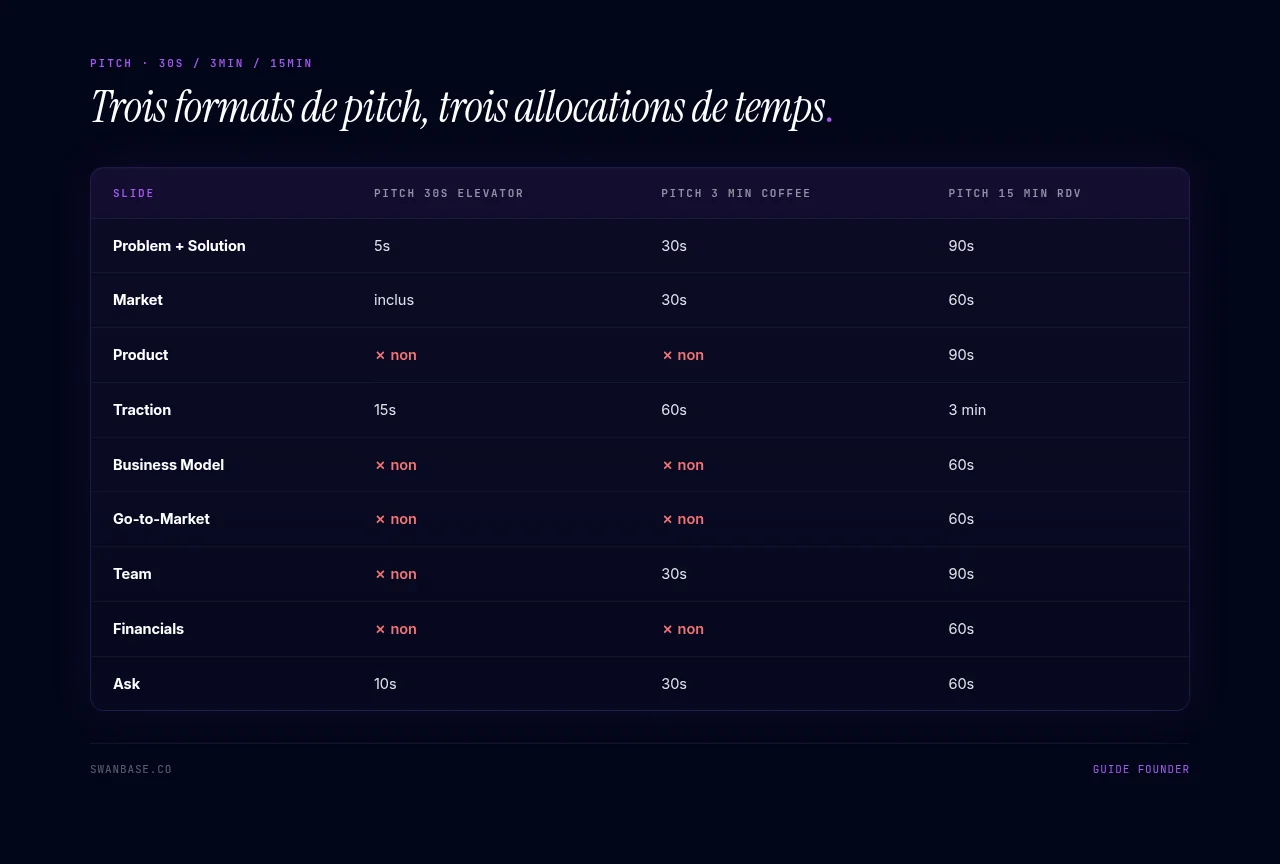
A pitch doesn't always last 15 minutes. Depending on the context, you'll have 30 seconds, 3 minutes, or 15. These are three distinct exercises, and each needs its own preparation.
The 30-second pitch (elevator)
You run into a VC at an after-work event, with about as much time as it takes to eat a canapé:
- 5s: "We do X for Y." (what, for whom)
- 15s: "We have Z in traction, in a W market." (proof + size)
- 10s: "We're raising €K to achieve L." (ask + use of funds)
If they're interested, they'll ask for more. If not, you've lost 30 seconds instead of 15 minutes.
The 3-minute pitch (first call / coffee chat)
The trickiest format: too short to say everything, too long to wing it. Allocation:
- 30s Problem + Solution
- 30s Market (with figures and sources)
- 60s Traction (the longest segment, and the decisive one)
- 30s Team
- 30s Ask
No slides. You just talk. At the end, ask one question: "Does this fit your thesis?"
The 15-minute pitch (in-person meeting or long Zoom)
Indicative allocation across the 10 slides:
- Slides 1-2 (Problem + Solution): 90s
- Slide 3 (Market): 60s
- Slide 4 (Product): 90s (demo if possible)
- Slide 5 (Traction): 3min (the key moment)
- Slides 6-7 (Business Model + GTM): 2min
- Slide 8 (Team): 90s
- Slides 9-10 (Financials + Ask): 2min
- Buffer: 3min for questions along the way
A long Q&A follows at the end. If the VC interrupts on slide 2, don't fight to stay linear: answer, then pick your thread back up.
Oral pitch vs. written pitch: two different exercises
A classic trap is using the same deck for the PDF sent ahead of time and for the live presentation. Bad idea. They're two different objects, read in two different contexts.
The PDF deck sent ahead of time
It gets read in 2 minutes, alone, on a screen, with nobody there to defend it1. So:
- Explicit text on every slide (otherwise the reader won't understand a thing).
- Dense slides, self-explanatory data.
- Nothing left to "explain in person": everything is written down.
- Footnotes citing the sources of your numbers.
The live pitch
You carry the story, and the deck supports it. So:
- Clean slides: one idea per slide, big visuals, little text.
- You talk, the VC looks at the visual, and your voice carries the message.
- Video demos beat static screenshots whenever possible.
- A one-line customer anecdote on slide 1 or 2.
The "reading" deck vs. the "presentation" deck
The simple fix is two versions. The reading deck (PDF, dense, self-explanatory) goes out before and after the meeting. The presentation deck (clean, visual) is what you project live. Same structure, two levels of density. Settle for a single version and you lose in both contexts.
The 10 trick questions French VCs ask (and how to answer them)
These are the 10 questions that come up most often in meetings, with scripts to answer them without losing your footing4.
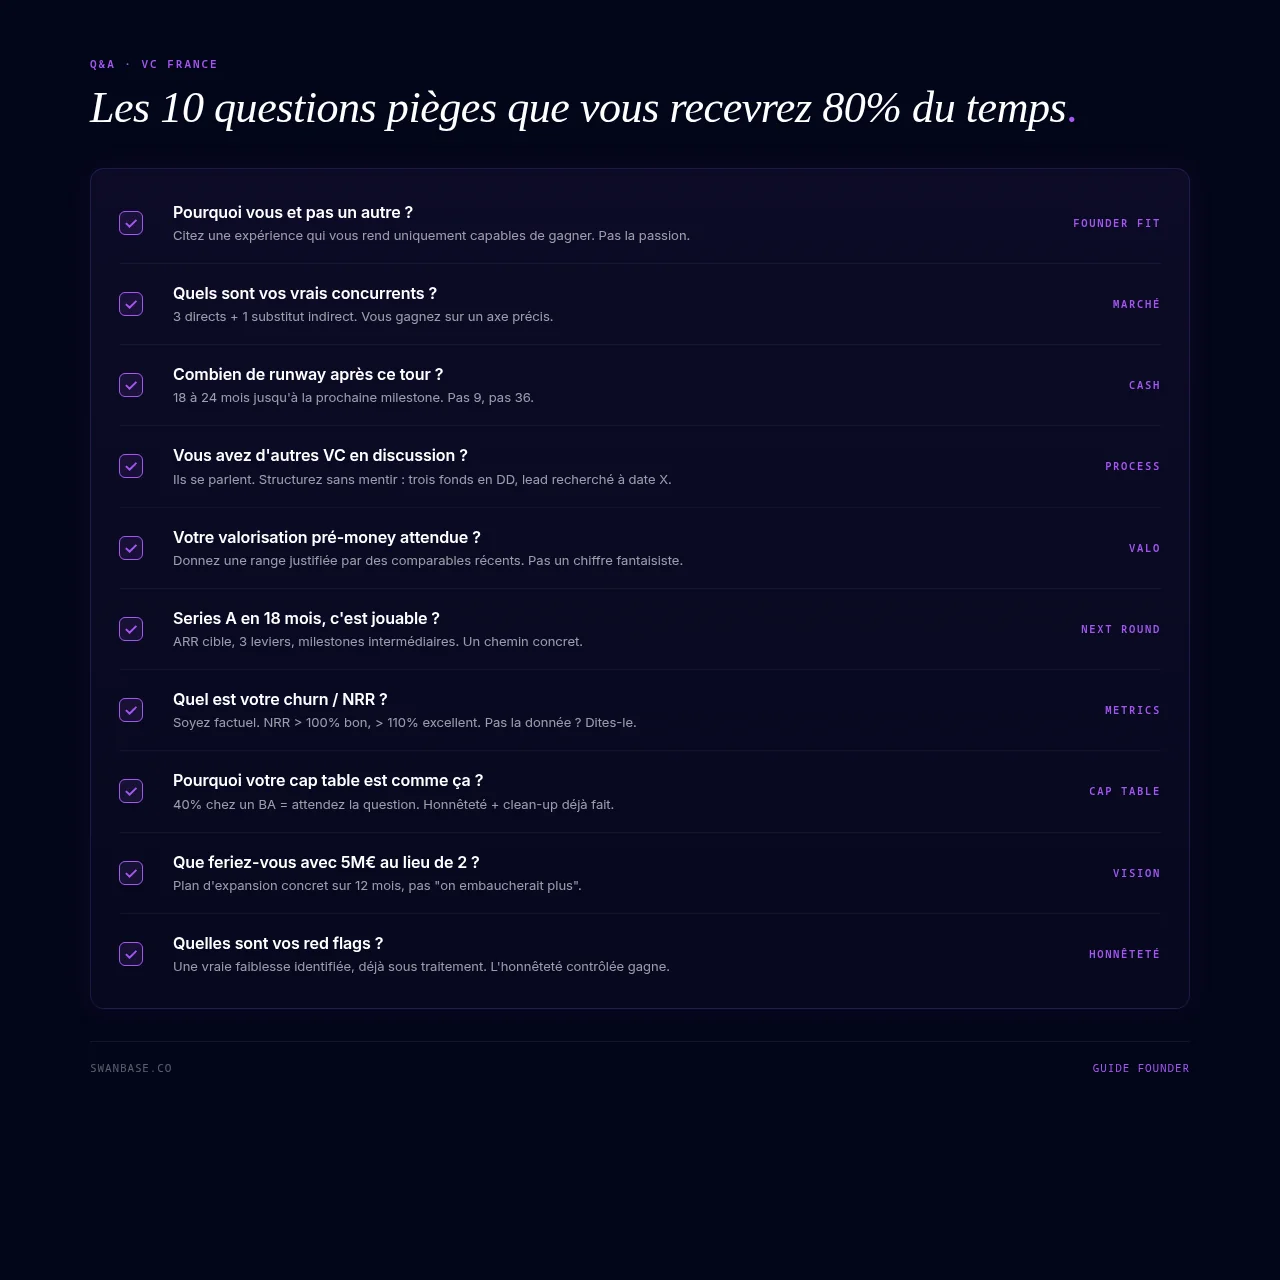
"Why you and not someone else?"
Worst answer: "We're passionate." A good answer is a fact: "We spent 4 years in [sector], we saw the problem from the inside, and we know the 3 reasons nobody has solved it so far." Cite an experience that makes you uniquely able to win.
"Who are your real competitors?"
Never say "We don't have any competitors." It's an instant red flag. Name 3 direct competitors and 1 indirect substitute. Explain why you win on one specific axis (speed, price, vertical, distribution).
"How much runway after this round?"
Expected answer: 18 to 24 months, enough to reach the next milestone (Series A, breakeven, target ARR). With 9 months, you'll be back raising from a position of weakness. With 36 months, you're burning too little to grow fast.
"Are you talking to other VCs?"
Don't lie: they talk to each other. But frame it: "Three funds are in due diligence, and we're looking for a lead by [date]." If you have nobody yet, say "We're starting conversations with 5 funds this week." It's honest, and it signals momentum.
"What pre-money valuation are you expecting?"
Give a range, not a fixed number. "We're targeting X to Y depending on the lead and the ticket." Back it up with recent public comparables (TechCrunch, Maddyness, Capital Finance). No fantasy figures.
"Can you reach a Series A within 18 months?"
The VC is testing whether you understand Series A KPIs: ARR above €1-2M for SaaS, MoM above 15%, NRR above 110%, a fleshed-out team. Answer with a concrete path: "By month 18, we're targeting [ARR goal] through [3 levers]. Here are the intermediate milestones."
"What's your churn / NRR?"
If you don't have the data, say so. Lying shows. NRR above 100% is good, above 110% is excellent. If NRR is below 90%, have an explanation ready (early cohort, segment you exited, pivot).
"Why does your cap table look like this?"
With a broken cap table, you lose the deal in thirty seconds. If you gave 40% to an angel, expect the question. Honest answer: "We made a choice 2 years ago, here's why, and here's how we've cleaned it up since." For contractual clauses (BSA, BSPCE, anti-dilution), see the term sheet clauses to negotiate.
"What would you do if I gave you €5M instead of €2M?"
This tests how elastic your vision is. Bad answer: "We'd hire more people." Good answer: "We'd accelerate EU expansion to 12 months instead of 24. Here are the 3 markets and the plan." Show that you'd know how to put more cash to work without wasting it.
"What are your own red flags?"
Worst answer: "We don't have any." Good answer: name one real weakness that you've already identified and are already addressing. "Our churn is 6% monthly in the SMB segment, and we have two initiatives underway to bring it down to 3% by Q3." Owning a weak spot earns more trust than pretending to be perfect.
The ask: how much to raise and how to defend it
It's the last slide, and one of the most frequently botched. Ask for too much and you look like you've miscalculated. Ask for too little and you'll run out before hitting your milestones.
Calculating your ask (runway × burn × milestones)
Formula: (monthly burn × 18 to 24) + (20% buffer) + (one-off investments). Burn = team + tools + acquisition + overhead, and don't forget payroll taxes (roughly ×1.42 on gross salary in France). A burn of €80k/month × 20 months of runway = ~€1.9M + buffer, so ~€2.3M.
Justifying the use of funds
A VC doesn't write a check, they fund milestones. Break it down:
- Team (X hires: who, when, why)
- Product (what to build, what value it creates)
- Acquisition (channels, target CAC)
- Buffer and operations
A clear use-of-funds slide saves you thirty minutes of Q&A.
Connecting to the term sheet
Once the pitch lands and the investor is interested, you move into negotiation. The trap at this stage is thinking you're home free and then losing on the clauses. It's a topic in its own right: the VC term sheet clauses to negotiate first (anti-dilution, liquidation preference, drag-along). For what comes next, from due diligence to closing, follow our guide to the stages of a fundraise.
Follow-up and reading VC signals
The pitch is over and you leave the room. Now begins the wait for an answer that doesn't always come on its own. Follow-up is an exercise in itself.
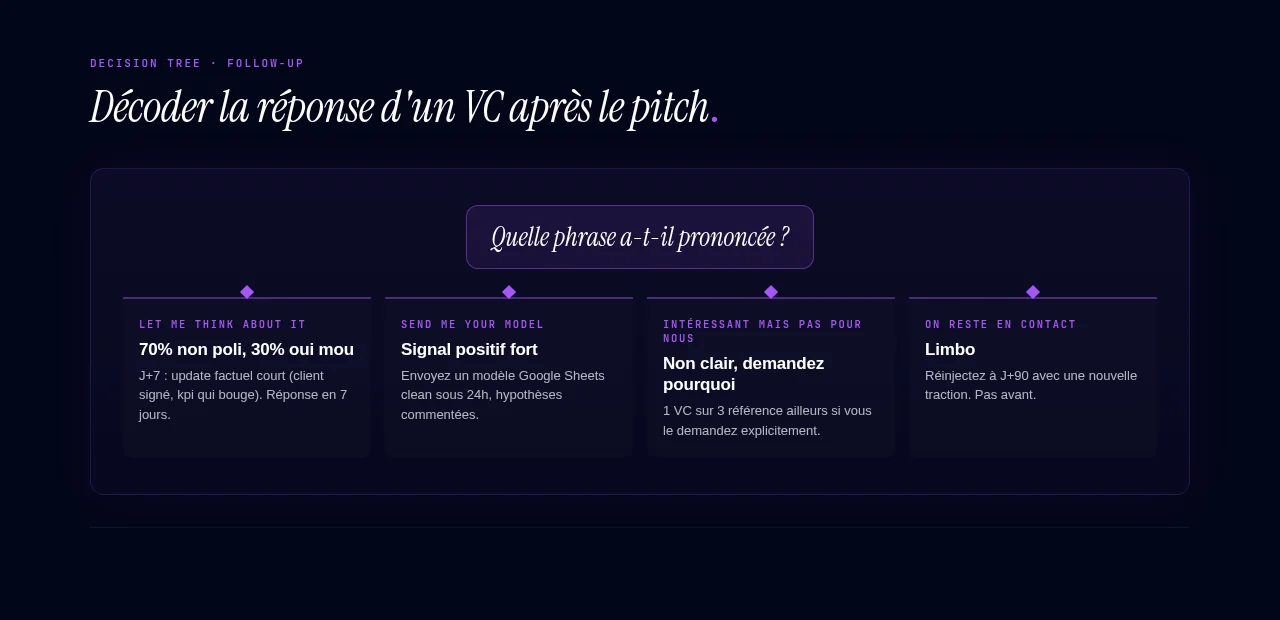
What "let me think", "send me a model", and "interesting, but we'll pass" really mean
Quick decoder:
- "Let me think about it." → A polite no in most cases. You'll know within 7 days.
- "Send me your financial model." → A strong positive signal. Send a clean model (Google Sheets, with commented assumptions) within 24 hours.
- "Interesting, but we'll pass." → A clear no. Ask why, specifically, and whether the VC can refer you elsewhere. Some will.
- "Let's stay in touch." → Limbo. Come back 3 months later with new traction.
How to follow up at 1 week, 1 month, 3 months
- Day 7: A short factual update (a signed customer, a KPI that moved). Skip "Have you decided?" and write "Quick update: we just signed X."
- Day 30: If there's no reply, send an explicit update: "We're finalizing our round with [lead] and are holding a spot if you're interested."
- Day 90: Closing: "We're closing the round next week. Last call if you'd like to participate." State it as a fact, with no hint of a threat.
When to give up on a fund
Three signals: no reply after 3 follow-ups, no intro to a senior partner after the first call, or endless due diligence requests with no written commitment. Don't spend 40% of your energy on 10% of your list.
Four fatal pitch mistakes
An overly optimistic market slide
"The global SaaS market is worth $200 billion." Fine. And what share of it do you actually address? A TAM-SAM-SOM without quantified assumptions costs you your credibility on the spot.
A team that isn't credible
Overly junior résumés with no complementarity, or two founders with exactly the same profile. A VC checks whether the team covers tech + go-to-market + operations. Two engineers in B2B SaaS leave a go-to-market gap. Acknowledge it and explain how you'll fill it (advisor, planned hire).
No defensible advantage
"We're simpler / faster / more user-friendly." Every one of your competitors says that. What's your structural advantage? Proprietary data, brand, network effects, switching costs? If the answer is "nobody else dared," you'll be copied within 6 months.
A broken cap table
40% held by an absent angel, 25% held by a co-founder who left 18 months ago and was never cleaned up, a free BSA signed with an accelerator with no cap. Any of these kills a deal before financial due diligence even starts.
FAQ
Should you send your deck ahead of time or wait for the meeting?
Send it ahead, always. A VC who shows up without having read your deck isn't serious. A VC who has read it comes in with targeted questions, and the conversation is far more productive. Send it 48 hours before, as an attachment or via DocSend (tracked link).
How many VCs should you contact in parallel?
15 to 25 funds in the first wave, over 6 to 8 weeks. Fewer means too little signal. More makes personalized follow-up impossible. Prioritize by fit (stage, ticket, sector) over prestige.
Should you sign an NDA before pitching?
No. No serious VC signs an NDA for a first pitch. Your execution is what protects you, since an idea on its own is easy to copy. Insist, and you'll be archived. Keep truly sensitive material (code, data, key contracts) out of the initial deck.
How long does a full VC round take?
4 to 9 months from first call to closing. Seed can move faster (3 to 4 months with clear traction). Series A is slower (6 to 9 months on average). If you have 6 months of cash when you start raising, you're already late.
Preparation determines most of your chances of getting a term sheet. swanbase supports early-stage founders over the long term, in Paris and remotely: free of charge, by application, and swanbase takes equity.
Footnotes
-
DocSend Pitch Deck Metrics: https://www.docsend.com/index/pitch-deck-metrics/ ↩ ↩2
-
Funding Blueprint 10-slide pitch deck structure: https://fundingblueprint.io/pitch-deck-10-slide-structure ↩
-
Sequoia Capital pitch template (bonus slides): https://www.lunarmobiscuit.com/pitching-sequoia/ ↩
-
15 fundraising mistakes (trick questions, due diligence, rejection signals): https://www.magstartup.com/erreurs-levee-de-fonds-15-pieges-qui-tuent-une-startup/ ↩