Your startup is in trouble, the runway is shrinking, and you realize that two or three BSA Airs signed 18 months ago are sitting forgotten in a Drive folder. What happens to that money if the company shuts down? There are four scenarios. 1) The deadline passes with no qualified round: forced conversion at the floor price, the investor comes onto the cap table at a bad valuation, and you get diluted. 2) Major pivot: the BSA Air stays alive on unchanged terms. 3) Voluntary dissolution: the investor holds an unsecured claim, paid only if cash is left after priority debts. 4) Court-ordered liquidation: the investor is at the back of the line behind salaries, URSSAF, the tax authorities and secured suppliers. In most cases, the investor gets nothing back.1 Safeguard: as soon as you see one of these scenarios coming, call a startup lawyer. This article explains when and why.
Quick refresher: how BSA Air conversion actually works
A BSA Air is a share subscription warrant: the investor puts in cash now and receives the right to shares later, at a discounted price. Conversion is triggered by a qualified round, an acquisition, or the deadline (typically 18 to 36 months). A BSA Air is not debt. It carries no interest, no cash repayment, and no shareholder status before conversion.2 The complete BSA Air guide covers the mechanics. This article deals only with the downside: your startup won't convert as planned.
The 4 "non-conversion" scenarios for a BSA Air
Most articles on the BSA Air describe the happy path: you raise your Series A, the warrant converts, everyone's smiling. The unhappy path gets two lines. When the market turns, that's the part that matters. There are four possible situations, each with its own rules and traps.
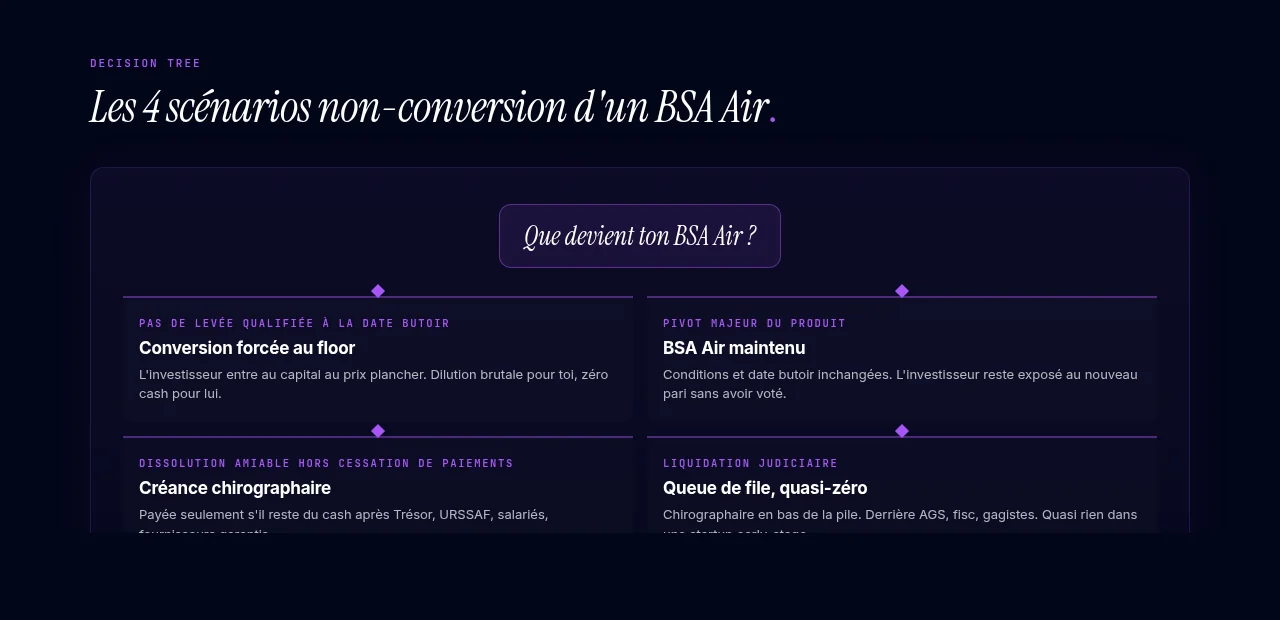
Scenario 1: No qualified round by the valuation date
You signed a BSA Air in March 2024 with a 36-month deadline, so March 2027. It's early 2027, there's no Series A in sight, and the clause kicks in. What happens depends on the contract. Case A, automatic conversion at the floor: the investor joins the cap table based on the original minimum valuation. If your floor was €3M pre-money and the company is now worth €1.5M, they still convert at €3M. They pay well above the current value of their shares, and your dilution stays capped. Without a floor, conversion would happen at the crushed valuation and they'd get far more shares. Case B, straight expiry: the BSA Air lapses and the investor gets nothing. This is rare in France and more standard with post-money SAFEs. Without an explicit expiry clause, forced conversion is the default.
Scenario 2: Major pivot
You change your product, sometimes your market. A pivot isn't a trigger event: the warrant stays alive, with the same terms and the same deadline. Your investor stays exposed to the new bet without having voted for it. Some contracts include a "material change of business" clause that allows the terms to be revisited. Check line by line.
Scenario 3: Voluntary dissolution
You decide at an extraordinary general meeting (EGM) to close the company before it becomes insolvent. A voluntary liquidator sells the assets, pays the debts, and distributes what's left to the shareholders. The BSA Air becomes an unsecured claim (créance chirographaire: no collateral, no priority): the investor waits in line behind the tax authorities, URSSAF, employees and secured suppliers. Creditors have 30 days after publication in the Bodacc to file an objection.3 Thin cash left over? The BSA Air gets nothing.
Scenario 4: Court-ordered liquidation
Insolvency, commercial court, court-appointed liquidator. Assets are sold and distributed in a strict legal order: super-priority creditors (AGS, the wage guarantee fund) → court costs → preferred creditors (tax authorities, URSSAF, secured lenders) → unsecured creditors.4 The BSA Air sits at the very bottom. When an early-stage startup that has burned through its cash gets liquidated, there's almost never anything left for unsecured creditors. And unlike preferred shares from a traditional round, the BSA Air has no liquidation preference.1 This is the harshest scenario.
What the investor recovers in each scenario
From the investor's side, the asymmetry is brutal: they paid cash going in, and they usually walk away empty-handed if the company fails.
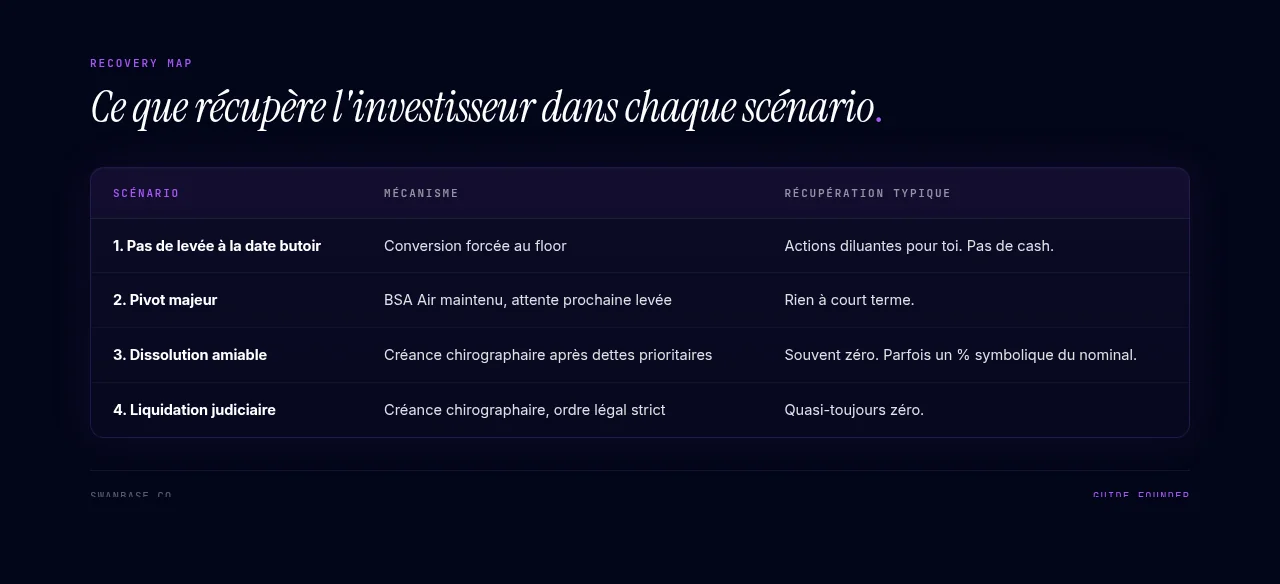
| Scenario | Mechanism | Typical recovery |
|---|---|---|
| 1. No round by the deadline | Forced conversion at the floor | Shares. No cash. Dilution capped by the floor. |
| 2. Major pivot | BSA Air stays in place until the next round | Nothing in the short term. |
| 3. Voluntary dissolution | Unsecured claim after priority debts | Often zero. Sometimes a token % of the face value. |
| 4. Court-ordered liquidation | Unsecured claim, strict legal order | Almost always zero. |
Scenario 1: forced conversion OR expiry
The investor comes onto the cap table at the floor. No cash: they become a shareholder in a struggling company. If the clause provides for expiry without conversion (rare in France), they lose everything.
Scenario 2: no automatic recovery
The BSA Air lives on and the investor waits for the next round. No liquidity, no exit, unless there's a specific buyback clause (very rare in French BSA Airs).
Scenario 3: unsecured claim in a voluntary dissolution
If €50K is left after salaries, taxes and suppliers, and they put in €100K, they get a fraction. Otherwise zero.
Scenario 4: near-total loss in a court-ordered liquidation
Unsecured creditors come after everyone else. In the vast majority of early-stage startup liquidations, the BSA Air is lost.
Safeguard
These scenarios describe the standard legal framework. Every BSA Air has its own clauses: a law firm may have slipped in a repayment clause, an early buyback option, even a personal guarantee from the founder (extremely rare, but it happens). You won't know until you reread the contract with a lawyer.
Expired valuation date: how it actually plays out
The deadline is the tipping point. You know when it is (or you should). It's in black and white in the contract. And yet there's a good chance you'll rediscover it six weeks before it hits.
Standard clauses at the deadline
There are three mechanisms. Conversion at the floor price: the default in the French market. Extension by mutual agreement: an amendment pushing the deadline back by 6 to 12 months. Conversion at a valuation negotiated on the date: less common, and it requires an independent valuation or an agreed figure.
Renegotiating with your angels to extend the deadline
Talk to your investors three to six months ahead, rather than three weeks before. Propose an amendment. Be open about the reasons (market, traction, next round planned in about 9 months). An angel will often prefer to push the date back rather than force you to convert in a company they no longer believe can raise. They also know the floor is worthless if the company dies two months later.
Voluntary dissolution vs court-ordered liquidation: the practical difference
People often call both procedures "liquidation" in everyday language. Legally, they're worlds apart.
Voluntary dissolution: a shareholder decision
It's decided at an EGM, while the company is still solvent. You choose to close. A voluntary liquidator (often an executive or an accountant) sells the assets, pays the debts in the legal order, and distributes the balance to shareholders. Expect a few thousand euros in fees and several months of procedure. If assets exceed liabilities, you return money to shareholders. If they don't, it switches to a court-ordered liquidation.
Court-ordered liquidation: the commercial court
You're insolvent (debts due exceed available assets). You must file for insolvency within 45 days. The court appoints a liquidator who takes control. Assets are sold and creditors are paid in the legal order. You no longer have the power to favor an investor, and trying to do so exposes you to criminal and civil liability (criminal bankruptcy, personal liability for the company's shortfall).
Where the BSA Air sits in each case
Voluntary dissolution: unsecured, behind priority debts, ahead of shareholders (but often with nothing to collect). Court-ordered liquidation: unsecured, at the bottom of the pile, behind AGS, the tax authorities, URSSAF and secured lenders. In both cases, no priority at all. It's a warrant, which puts it in a different category from a convertible bond, secured debt, or a preferred share with a 1x liquidation preference.1
Do some BSA Airs include repayment clauses?
In principle, no: by design, there's no cash repayment.2 But contracts negotiated at the margins can contain things no template covers.
Early buyback clauses (rare in France)
Some custom BSA Airs give the company the option to buy back the warrant for a set amount (face value plus a premium). This clause requires available cash, so it saves no one in an insolvency. It's useful after a pivot or a post-signing misalignment.
"Minimum return" clauses
Inspired by the US post-money SAFE, some variants provide a minimum amount owed to the investor on exit. They're almost nonexistent in French BSA Airs. Don't confuse this with the liquidation preference on preferred shares, which applies to shares, and never to unconverted warrants.
How to check whether your BSA Air has one
Reread three sections. Conversion terms: look for the words "rachat" (buyback), "expiration", "caducité" (lapse), "résiliation" (termination). Company undertakings: sometimes there's a conditional buyback promise. Financial appendix: the warrant's face value, subscription premium, and any repayment formula. If you see nothing, there's probably nothing. Confirm with your lawyer.
When to see a lawyer (founder warning signs)
This is a legally sensitive topic. The line between sound handling of a difficult situation and mismanagement (which can make you personally liable for the company's shortfall) is thin. These are the signals that call for a meeting right away, rather than in two months.
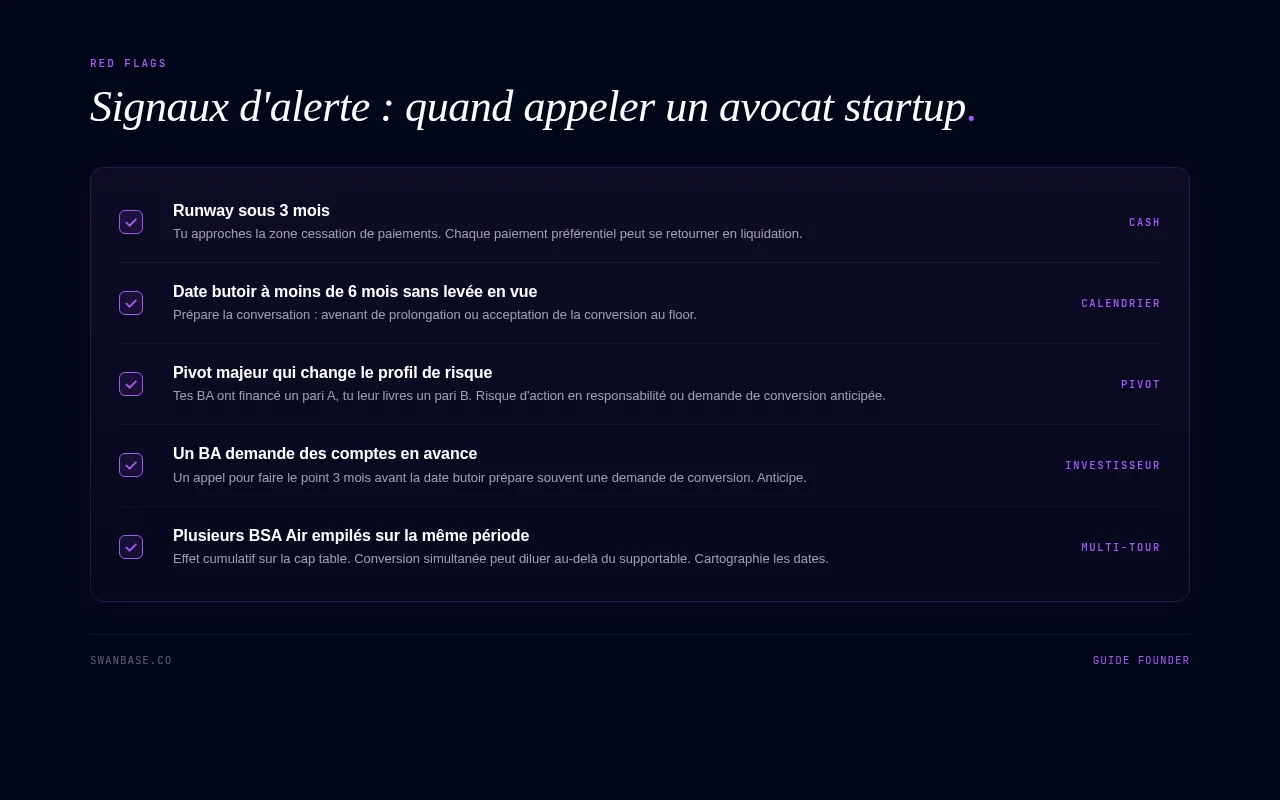
Runway under 3 months
With less than three months of cash, you're approaching insolvency territory. Every decision (paying one creditor ahead of others, taking on a new commitment, giving a raise) can be turned against you in a liquidation. A startup lawyer, ideally alongside a court-appointed ad hoc mandatary (mandataire ad hoc), keeps you safe.
Valuation date under 6 months away with no round in sight
Prepare the conversation with your investors: an extension amendment or acceptance of conversion at the floor. Your lawyer drafts the documents (amendment, EGM minutes, subscription form).
Major pivot that changes the risk profile
Your investors funded bet A, and you're delivering bet B. The risk: a liability claim (rare but possible) or a request for early conversion.
A BSA Air investor asks for an update ahead of time
An angel who calls to "check in" three months before the deadline is sending a signal. They're often preparing a conversion request or legal action. Get ahead of it with an advisor.
Finding a lawyer who knows startups
Several Paris firms cover this: SB Avocats (the inventors of the BSA Air), OMADA, Squair, Alkeom, Hashtag, and Kickston on the financial advisory side. Platforms like SeedLegals handle simple cases (amendments, conversion at the deadline). For the downside scenario, go to a law firm.
Communicating with your BSA Air investor when things get tough
Handle it badly and you turn a disappointed investor into a litigious one. Handle it well and you keep an ally for your next company (because there will be a next one).
Proactive transparency
Monthly or quarterly once things get tight. Keep the update short: cash, runway, key metrics, next major decision. An angel who learns about the dissolution from a liquidator's email switches into litigation mode. An angel who watches the situation deteriorate month after month stays pragmatic.
Clear boundaries
What you must avoid: verbally promising a repayment, guaranteeing conversion at valuation X, or committing to favor a particular investor. All of that exposes you to criminal liability in a liquidation (criminal bankruptcy, preferential payments). Say what you know and what you don't, and promise nothing.
A structured request
If you're asking to extend the deadline, do it in writing, with an amendment ready to sign and a credible fundraising timeline. A vague phone call won't cut it.
Founder mistakes to avoid when things get tough
Three classic traps when the BSA Air becomes a burning issue.
Ignoring the approaching valuation date
You know it's coming, and you do nothing. On the day, the investor triggers conversion at the floor and you end up diluted without having negotiated anything. Set a reminder 9 months ahead.
Verbally promising your angels a repayment
Under pressure, you let slip "don't worry, we'll get your money back to you." If the company closes, that sentence can cost you dearly. The BSA Air doesn't allow for repayment.2 Any promise to the contrary exposes you personally.
Skipping pivot approval when the contract requires it
Some contracts include a duty to inform, or even a right of review, over major pivots. If you skip that step, expect a request for early conversion or a liability claim. Reread the contract before you pivot.
FAQ
Can a BSA Air block a voluntary dissolution?
No. The BSA Air investor can only act indirectly. The dissolution is decided by the shareholders at an EGM. As an unsecured creditor, the BSA Air investor can file an objection within 30 days of publication in the Bodacc.3 An objection delays the dissolution but can't block it permanently: the court decides.
Do you have to repay business angels if the startup fails?
No, unless there's a specific contractual clause. The BSA Air is a subscription warrant and carries no debt: by default, there's no cash repayment.2 The investor takes on equity risk and accepts it at signing. Any verbal promise that contradicts the contract can make you personally liable.
Do angels have oversight rights during the life of the BSA Air?
Limited by default. The BSA Air doesn't confer shareholder status before conversion: no voting rights, no invitation to general meetings, no dividends. Some contracts provide for periodic reporting or a right of review over major pivots. Check your contract.
How much does a lawyer consultation cost when you're in trouble?
Many startup law firms offer the first meeting for free. A simple amendment or contract review: €800 to €2,000 excl. VAT. A financial distress file (ad hoc mandate, negotiation, dissolution prep): €3,000 to €10,000 excl. VAT depending on complexity. Platforms like SeedLegals: flat-fee packages from €500 for simple documents.
The BSA Air is a defensive bridge tool when the market is healthy. When it turns, the deadline lands at 18 or 36 months. First line of protection: read the contract before signing (floor, deadline, trigger events, oversight rights). Second: call your lawyer six months before the red zone, rather than six weeks after. To go further: complete BSA Air guide, discount, cap and floor, cap table impact, BSA Air vs SAFE, bridging with a BSA Air.
Footnotes
-
https://www.maddyness.com/2024/03/12/le-bsa-air-reste-t-il-toujours-loutil-indispensable-de-lamorcage/ ↩ ↩2 ↩3
-
https://eldorado.co/blog/2021/12/09/le-bsa-air-en-theorie-et-en-pratique ↩ ↩2 ↩3 ↩4
-
https://entreprendre.service-public.gouv.fr/vosdroits/F23744 ↩ ↩2
-
https://dissolution.comptable-en-ligne.fr/r/creanciers-privilegies-et-creanciers-chirographaires ↩